May was an exceptional month for global equity markets (MSCI World +4.6% MoM/+10.7% YTD), which extended April’s gains, defying historical seasonal trends (May is a relatively modest month for US markets, hence the adage “sell in May and go away”). Equity markets were driven by three dominant themes: the artificial intelligence (AI) capex supercycle, robust 1Q26 US earnings, and growing optimism around a possible US-Iran deal that will ease the oil price shock.
US macroeconomic data released in May showed that April headline inflation rose 3.8% YoY vs March’s 3.3% print, the highest since May 2023. Core inflation, which strips out food and energy, increased by 2.8% YoY from 2.6% previously, well above the US Federal Reserve’s (Fed) 2% goal. April core personal consumption expenditure (PCE), excluding food and energy, the Fed’s preferred inflation gauge, climbed 3.3% YoY, vs March’s 3.2% – the highest reading since November 2023.
US equities soared to record highs, driven by impressive earnings (c. 83% of S&P 500 companies beat estimates), AI capex spending, and reports on 29 May that the US and Iran had reached a memorandum of understanding to extend the ceasefire. The tech-heavy Nasdaq led the gainers (+8.4% MoM/+16.1% YTD), notching new highs with NVIDIA being the primary catalyst as it posted 1Q27 results which showed hyperscaler capex collectively running at c. US$725bn for 2026 (+77% YoY). The S&P 500 rose 5.1% MoM (+10.7% YTD), while the Dow ended 2.8% higher MoM (+6.2% YTD).
European equity markets advanced but lagged the US and Japan, with the Euro Stoxx 50 up 2.9% MoM (+4.5% YTD), remaining below pre-Iran War levels. With fewer AI and tech-focused companies vs the US and Asia, the region is less able to benefit from the AI rally that helped drive outperformance elsewhere. France’s CAC rose 0.8% MoM (+0.4% YTD), and Germany’s DAX jumped 3.3% MoM (+2.5% YTD). April eurozone inflation rose to 3.0% vs March’s 2.6%, driven largely by higher energy costs. As a major net energy importer, Europe is especially vulnerable to energy shocks.
May was a volatile month for UK equity markets, with the FTSE 100 barely changed vs end-April’s level (+0.3% MoM/+4.8% YTD). April inflation surprised to the downside, printing at 2.8% YoY vs March’s 3.3%. The Office for National Statistics said energy costs had fallen due to a combination of lower wholesale prices and the government’s energy bill support measures introduced before the start of the Iran conflict. Unfortunately, this improvement in inflation is likely to be short-lived.
In China, equity markets, which had a broadly positive May, saw gains fade into the month-end as investors took profit in tech and semiconductor shares. The Shanghai Composite was down 1.1% MoM (+2.5% YTD) and the Hang Seng declined 2.3% MoM (-1.7% YTD). May’s official manufacturing PMI printed at 50 vs April’s 50.3, matching the 50-point mark that separates expansion from contraction. Non-manufacturing PMI, including services and construction, came in at 50.1 vs 49.4 in April.
Japan’s benchmark Nikkei soared 11.9% (+31.8% YTD), the strongest performance among major global equity indices and surpassing the 66,000 level for the first time in its history. The equity market was powered by the AI-investment cycle and an ongoing structural rerating of Japanese equities. Headline inflation printed at 1.4% in April vs March’s 1.5%, remaining below the Bank of Japan’s 2% target for a fourth consecutive month.
Brent crude (-19.3% MoM/+51.3% YTD) had another volatile month, as oil prices swung wildly in May, before ending the month lower at US$92.05/bbl. Outside of oil, commodity performance was mixed. Gold (-1.7% MoM/+5.1% YTD) was notably weak, continuing a correction from all-time highs set earlier this year. Platinum group metals (PGMs) remained under pressure, mirroring the broader precious metals correction. Platinum declined 3.4% MoM (-6.8%YTD), despite tight supply from SA and Russia and strong demand from China, with palladium down 11.2% MoM (-16.0% YTD) and rhodium falling by 12.0% MoM (-4.1% YTD).
The JSE consolidated in May, with the FTSE JSE All Share Index (-0.3% MoM/-1.0% YTD) ending the month basically flat. Mining shares remained under pressure as precious metals prices pulled back, weighing on large index constituents such as Gold Fields (-9.9%), Sibanye Stillwater (-1.8%), Northam (-1.4%), and Impala Platinum (-0.2%), which closed May lower. These losses offset firmer financial and property counters, leaving the market largely rangebound. Unlike many global peers, the South African (SA) equity market lacks significant exposure to large tech companies and thus benefited less from the global AI-driven rally. Resources were again the weakest segment (Resi-10 -1.7% MoM/+1.0% YTD), while the SA Listed Property Index advanced by 0.2% MoM (-1.0% YTD) and financials firmed (Fini-15 +0.8% MoM/+2.6% YTD). Industrials ended May lower (Indi-25 -0.9% MoM/-7.8% YTD). The rand strengthened 2.7% MoM (+2.1% YTD) against the greenback, helped by a combination of domestic rate hikes and softer US economic data, which drove a weaker US dollar.
SA headline inflation accelerated to 4.0% YoY in April from 3.1% in March. Over the same period, core inflation rose to 3.6% YoY from 3.2% previously. The higher inflation print reflects the initial pass-through of elevated global oil prices into domestic inflation. At its meeting on 28 May, the South African Reserve Bank (SARB) raised the repo rate by 25 bpts to 7%, citing heightened inflation risks and the increasing likelihood of second-round effects.
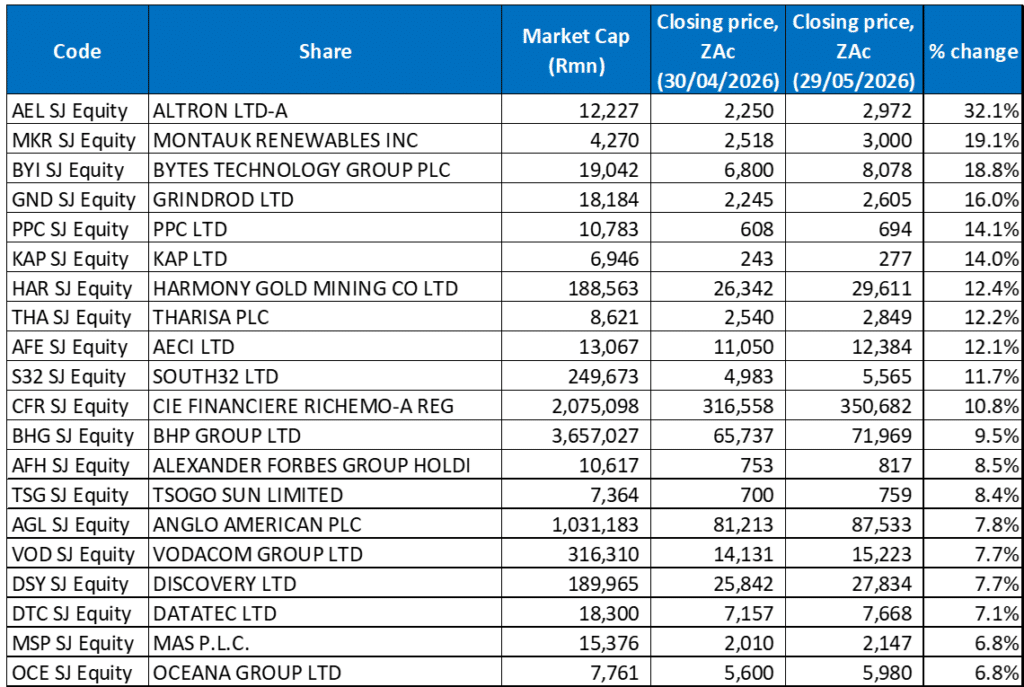
Figure 1: The 20 best-performing shares in May 2026, MoM % change
Source: Bloomberg, Anchor Capital
May’s winning shares included companies from sectors such as technology, industrials and select financials, while hospitality and gaming counters showed some resilience, and Harmony Gold bucked the precious metals sell-off trend.
Altron, one of the JSE’s most credible domestic tech plays, which operates across managed services, digital transformation, its own platforms (including vehicle recovery business Netstar) and its fintech and healthtech businesses, was May’s best performer with a 32.1% gain. The share price leapt more than 15% on 25 May after Altron reported a hike in its FY26 dividend and a special R500mn dividend payout. Group revenue advanced only 1% YoY to R9.6bn, but headline earnings per share (HEPS) jumped 34% YoY, driven by technology services demand. Altron has undergone a three-year strategic overhaul that its CEO set out in 2023, and which has shifted the company decisively towards its platform business.
Montauk Renewables, the US Nasdaq-listed biogas company with a secondary listing on the JSE, had another strong month with its share price up 19.1% in May. Montauk, which had been a JSE laggard for a long time, was the month’s second-best-performing share. Its continued gains were likely driven by a combination of factors, including higher oil prices (which meaningfully improve the economics of renewable natural gas as an alternative fuel source), while the bigger geopolitical backdrop around energy security has led investors to look for clean energy plays on the JSE.
In third place, Bytes Technology, listed locally and on the London Stock Exchange, rose 18.8% MoM. The company’s shares have soared due to its return to strong second-half profitability, continued demand for AI and cloud services, and the launch of a new GBP25mn share buyback programme. In May, Bytes reported FY26 revenue growth of 1.6% YoY to GBP220.5mn, while HEPS declined 6.1% YoY to GBp21.4. However, it recorded strong second-half (2H26) momentum during which it overcame the drag caused by Microsoft’s shift to consumption-based incentives, posting an 11.5% YoY jump in 2H revenue and better-than-expected gross invoiced income.
Logistics and port terminals operator Grindrod’s (+16.0% MoM) share price gains were likely built on the continued positive momentum from its March results, port throughput recovery (despite commodities volumes being under pressure) and rand-hedge earnings from its shipping operation. The company has experienced record throughput at the Port of Maputo, and the ongoing rollout of rail reform in SA, which is opening third-party access to the country’s national rail network and expanding Grindrod’s operational footprint and growth pipeline, is likely also benefitting sentiment.
Grindrod was followed by PPC Ltd, KAP Ltd and Harmony Gold with MoM gains of 14.1%, 14.0%, and 12.4%. PPC shares rose after the Group said in a trading statement that its FY26 HEPS would increase by between 20% and 33% YoY. In addition, media reports in May indicated that German multinational Heidelberg Materials was in talks to appoint financial advisers in preparation for a bid for PPC. Harmony Gold, rather counterintuitively (given the gold price’s decline in May), found itself among the ten best performing shares, after the gold miner said it was on track to meet full-year production, grade and cost guidance following a 5% uptick in its 3Q output. In its operational update, Harmony reported revenue of R68.4mn for 9M26 – up more than one-third from the previous comparable period.
Tharisa plc, an integrated resource Group that mines, processes, and beneficiates PGMs and chrome concentrates, rose by 12.2% MoM. Its share price surged after Tharisa flagged a bumper 1H26 financial report showing a nearly fivefold increase in profit. HEPS for the six months to March 2026 were expected to come in between USc16.1 and USc16.6 (c. R2.65 to R2.74), representing a YoY increase of between 455% and 472%. Revenue was expected to rise by 28% YoY to US$359.4mn.
Rounding out May’s ten best-performing shares were AECI Ltd and South32 with price gains of 12.1% and 11.7%. AECI has benefitted from a combination of its February results and its fundamental business positioning, with rising mining sector activity driving demand for its speciality chemicals and explosives. In addition, fertiliser prices, particularly urea, have surged over 80% between March and April, which is especially beneficial for AECI’s chemicals segment, supplying agricultural products.
Unlike gold and PGM miners, which sold off in May, South32 benefitted from its diversified commodity exposure; its portfolio of aluminium, copper, manganese, zinc and silver held up well. It has also been helped by the successful post-cyclone recovery of its Australian manganese operations and robust recent operational earnings that exceeded analyst expectations.
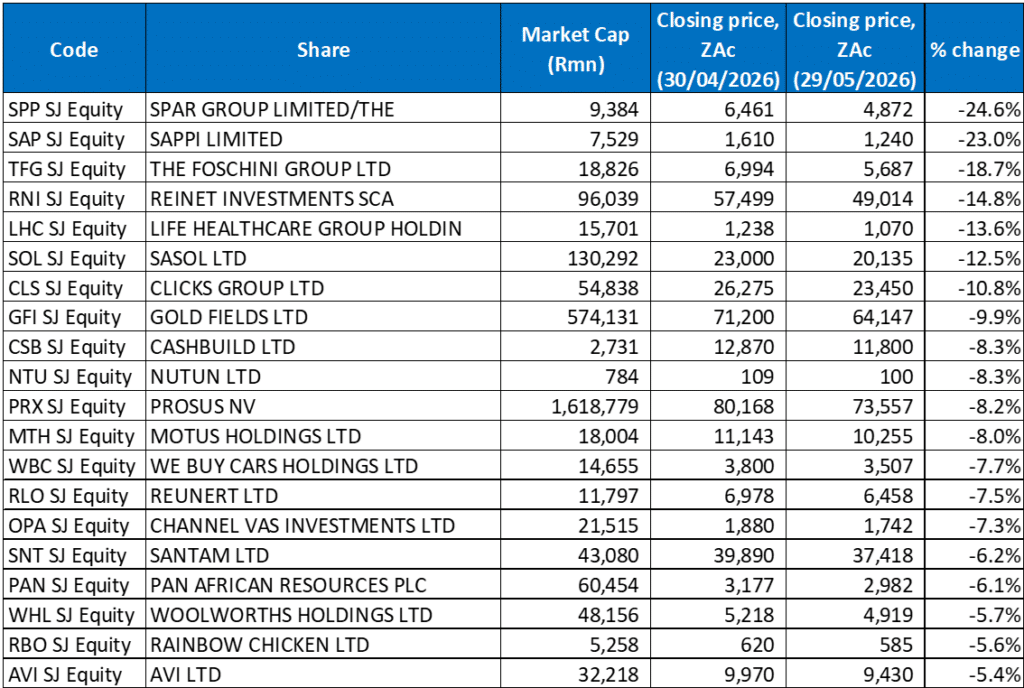
Figure 2: The 20 worst-performing shares in May 2026, MoM % change
Source: Bloomberg, Anchor Capital
Precious metals were the weakest sector by some distance, reflecting a further pullback in gold and PGM prices through May. Beyond precious metals, energy-sensitive businesses, and discretionary consumer names bore the brunt of May’s headwinds (the oil shock, rising inflation, and the SARB rate hike).
The SPAR Group (-24.6% MoM), which has been under pressure due to operational challenges following its troubled SAP system implementation, continued weakness in its European business, and consumer pressure across multiple geographies, which has compounded an already difficult turnaround story, was last month’s worst-performing share. Last week, the share price plunged further after it released a 1H26 profit warning wherein the retailer flagged that HEPS would decline by up to 60% YoY, driven by deep margin compression, rising operational costs, legacy issues, and executive changes.
SPAR was followed by Sappi Ltd with a 23.0% MoM share price decline, reflecting a company under severe structural pressure. The global paper and pulp business’s earnings are highly sensitive to global industrial demand and the rand exchange rate. Weak commodity pricing and margin pressure from elevated energy inputs (directly linked to the oil shock) have also weighed on the price. On 7 May, Sappi’s share price slumped over 11% after it posted a US$413mn (c. R6.7bn) 2Q26 loss compared with a US$20mn profit the year before, with expectations that 3Q26 may be worse.
In third place, clothing retailer The Foschini Group (TFG) was down 18.7% MoM. TFG released a trading statement in May, warning shareholders that it would report a worse-than-expected 30% to 40% YoY drop in HEPS due to weak domestic trading, a R750mn brand values impairment and higher interest. The clothing and accessories retailer, which operates in SA, the UK, and Australia, said it expects FY26 HEPS to be between ZAc609,4 and ZAc710,9, compared with ZAc1,015,6 in FY25.
Reinet Investments, Life Healthcare and Sasol followed TFG with MoM declines of 14.8%, 13.6%, and 12.5%, respectively. Reinet’s share price fell after it reported a 4.5% YoY decline in its FY26 net asset value (NAV) to EUR6.6bn. This decrease in the overall portfolio value was driven primarily by a weakening of the British pound and US dollar against the euro. Life Healthcare initially declined after it released a disappointing trading update in early May. The hospital group then posted its results last week, which showed that revenue grew by a modest 2.4% YoY to R12.4bn, while normalised EPS increased by 8.4% YoY. However, the outlook was disappointing, with the 12 months to September 2026 expected to see growth of only c. 2% YoY, weaker vs its competitors. Sasol’s share price faced downward pressure due to a combination of weaker oil prices, depressed international chemical prices, and a stronger rand.
Clicks Group’s (-10.8% MoM) share price decline has primarily been driven by a disappointing FY26 profit outlook, ongoing supply chain disruptions, and rising market competition. The company said in April that it expected slower FY26 earnings growth of between 4% and 9% YoY, which fell short of market expectations. More fundamentally, a constrained local consumer environment with reduced household spending has led to softer retail sales growth compared to previous years. Higher fuel prices, driven by the oil shock, will translate directly into increased pressure on household budgets (and thus discretionary spending), which eventually flows through to Clicks’ retail pharmacy, health and beauty volumes.
Gold Fields (-9.9% MoM), Cashbuild and Nutun (both down 8.3% MoM) rounded out May’s ten worst-performing shares. Gold Fields’ recent share price struggles stem from a combination of the precious metals selloff (gold price -1.7% MoM), operational challenges, geopolitical pressures, and sector-wide market volatility. Cashbuild’s share price has faced significant turbulence and is down primarily due to the strain on consumer spending from rising food and fuel costs.
Finally, Nutun’s share price fell due to a combination of heavy legacy debt, declining earnings, and challenging market conditions. In May, Nutun released 1H26 results, which showed that sales were R711mn compared to R745mn a year ago, while it recorded a net loss of R63mn compared to the R122mn loss in 1H25. Nutun has suffered a multi-year decline in EPS, driven by restructuring costs, macroeconomic headwinds and the fallout from the SA Taxi business during its time as a subsidiary of Transaction Capital.
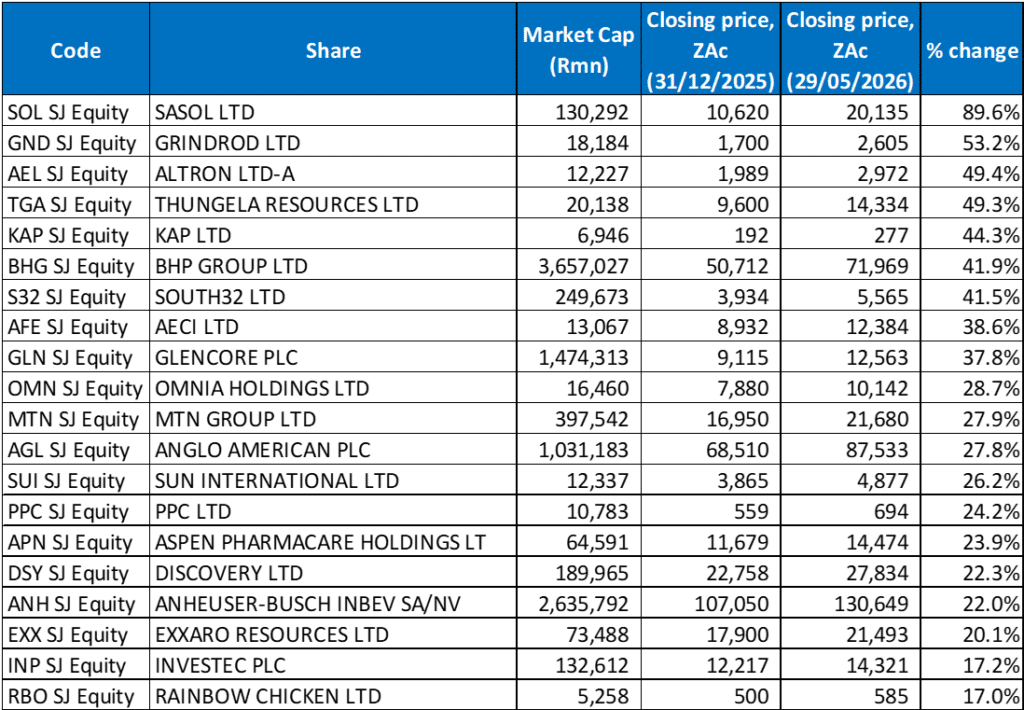
Figure 3: The 20 best-performing shares YTD, % change
Source: Bloomberg, Anchor Capital
Seventeen of the 20 best-performing shares YTD were unchanged from the year to end-April’s best performers, as gold and PGM counters were pushed out again following another turbulent month for precious metals. The common thread across these shares was direct or indirect leverage to the energy shock that has defined global markets this year, and companies that sell what people cannot stop buying, regardless of geopolitics.
Despite a share price decline in May, Sasol (+89.6%) remained the best-performing share YTD. Sasol, leading the YTD table, summarises the oil price trajectory in 2026 as the closure of the State of Hormuz and ensuing oil shock drove Sasol’s earnings expectations sharply higher. It is one of the few SA counters that structurally benefits from the very shock that is pressuring the broader economy – higher oil prices flow almost directly into its synthetic fuels margins, making it the purest JSE-listed energy play. In addition, as part of its integrated chemicals and energy business, Sasol sells various chemical and petrochemical feedstocks (coal-based and domestically sourced – protecting it from supply shocks that are impacting pure-play importers).
Following its impressive monthly gains in May, Grindrod moved up a few notches from April to take second place as its YTD gain jumped to 53.2%, reflecting SA’s improving logistics infrastructure story. Altron, May’s best-performing share, came third among the strongest performers YTD (+49.4%), supported by continued execution of its technology-focused growth strategy.
Altron was followed by Thungela Resources (+49.3% YTD), KAP Ltd (+44.3% YTD), and BHP Group (+41.9% YTD). Thungela’s YTD share price gain is due to a combination of sustained demand for thermal coal in developing Asian markets and broader market shifts toward traditional energy producers during periods of geopolitical uncertainty. The ongoing energy supply disruption environment has prompted Asian nations to substitute coal for oil and LNG, initially sending thermal coal prices to 18-month highs of c. US$146/tonne in March. While prices have since retreated, they seemed to find a floor in May at c. US$130/tonne on Chinese supply concerns. BHP, South32 (+41.5% YTD) and Glencore (+37.8% YTD) are also benefitting from their diversified commodity exposure across coal, copper, and energy transition metals, all of which have seen demand and pricing support since the start of the Iran war.
AECI (discussed earlier) rose 38.6% YTD, while Omnia (+28.7% YTD) rallied to multi-year highs, ending May above the R101/share mark. In its recent FY26 trading update, Omnia projected its full-year HEPS would jump by between 17% and 23% YoY. Omnia is one of SA’s largest producers and suppliers of fertiliser. While it is heavily exposed to sulphur and ammonia prices coming from the Middle East, the surging demand for critical minerals and commodities, coupled with higher global prices for agricultural chemicals, has boosted its outlook.
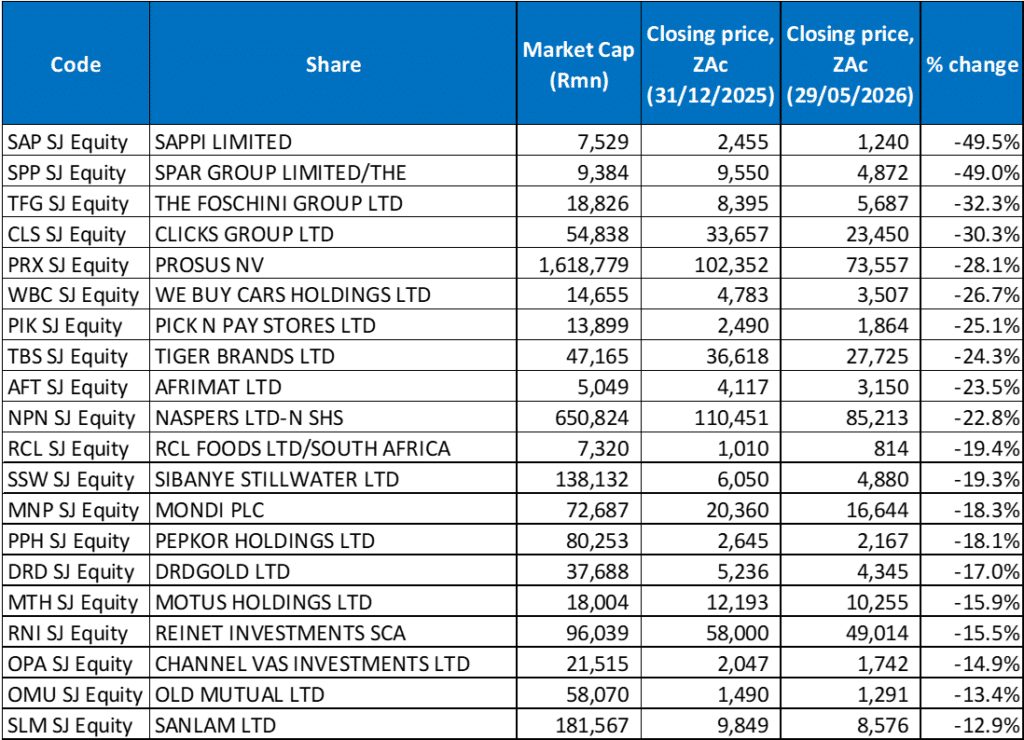
Figure 4: The 20 worst-performing shares YTD, % change
Source: Bloomberg, Anchor Capital
The JSE has been an extremely bifurcated market since the Iran conflict began. While energy stocks and select technology names continue to celebrate, other cohorts of JSE-listed shares are down significantly, with most of the YTD worst performers sharing a common vulnerability – SA consumer-facing businesses at a time of acute and sustained cost pressures (inflation, rate hikes and ensuing higher food and fuel costs). In addition, gold miners and industrials have been negatively impacted by their own sector-specific headwinds.
Sappi (discussed earlier) was again the worst-performing share YTD – down 49.5%. Spar (-49.0%), TFG (-32.3%), Clicks (-30.3%), WeBuyCars (-26.7%), and Pick n Pay’s (-25.1%) YTD share price declines reflect the tough operating environment facing local retailers, including, in the case of WeBuyCars, the impact of a weakening appetite for used vehicles as consumers prioritise essential spending. Higher oil prices feed directly into increased logistics costs, squeezing margins already under pressure from aggressive competitor pricing and a SA consumer whose disposable income has been eroded by the high cost of living.
Tiger Brands (-24.3%) faces the same inflationary headwinds as the retailers with higher input costs from oil-linked petrochemicals and food commodities that cannot be fully passed on to price-sensitive consumers, while Afrimat (-23.5%) has been negatively impacted by iron ore price volatility and risk-off sentiment towards smaller mining names.
Investment conglomerates Prosus (-28.1%) and Naspers’ (-22.8%) share prices have been soft YTD on the back of their largest investment, Chinese tech giant Tencent’s (-9% MoM/-29.0% YTD) uneven trajectory including AI disruption fears (concerns that AI will “cut out the middle man” when it comes to platform businesses like Tencent), the ongoing NAV discount problem and their 2025 share price rallies (both were up over 30% in 2025).
South Side Hard Soda Expands to 2,000 Retail Outlets. South African ready-to-drink beverage brand South Side Hard Soda has entered a new phase of growth following its acquisition by WV Squared Distribution, a member of the Richmark Group.
The acquisition marks a significant milestone for the brand as it expands its national footprint and strengthens its production capabilities in response to growing demand.
According to the company, the transaction provides South Side Hard Soda with access to expanded distribution infrastructure and operational resources aimed at supporting the brand’s continued growth within South Africa’s ready-to-drink (RTD) beverage market.
A key component of the expansion strategy has been a major manufacturing investment by a subsidiary within the group. Over the past year, the company commissioned and developed a dedicated canning line and production facility to support the brand’s future supply requirements.
The investment is intended to improve production capacity and ensure consistent product availability as distribution continues to expand across the country.
A representative for the brand said the additional manufacturing capability would help maintain reliable stock levels for retailers and consumers.
The latest expansion has seen South Side Hard Soda increase its retail presence to more than 2,000 outlets nationwide.
The brand is now available through several major liquor retail chains and independent outlets, including TOPS at SPAR, Pick n Pay Liquor, Johnny’s Liquor Hyper, Norman Goodfellows, Ultra Liquors and Liquor City.
The company said the expanded retail network significantly strengthens the brand’s national reach and positions it for further growth within the competitive RTD category.
South Side Hard Soda markets itself as a flavour-focused beverage option aimed at consumers seeking lighter alternatives within the alcoholic drinks market.
According to the company, the range contains lower levels of carbohydrates and sugar and is targeted at consumers looking for a lower-calorie beverage option without sacrificing flavour.
The acquisition and accompanying production investment represent an important development for the brand as it seeks to build on its existing customer base and establish a stronger presence across South Africa’s retail landscape.
The Congress of South African Trade Unions (COSATU) urges government to provide further Fuel Levy relief to cushion embattled workers and the economy from the massive fuel price hikes that have wreaked havoc since the commencement of the war in the Persian Gulf.
Whilst we appreciate the modest initial decrease in diesel prices due to come into effect, a further rise in petrol prices will be yet another painful blow that millions of struggling workers and commuters, and an already stagnant economy stuck at anemic 1% growth, simply cannot afford.
We fear that workers, society and the economy will not cope with the planned end in the fuel levy relief in July if international oil and fuel prices continue to remain abnormally high and even rise. Oil and fuel supplies and prices may also take some time to return to pre-war levels even once the war ends.
Diesel is critical for the public and private transport that workers depend upon as is paraffin for millions of working-class families. Workers who are already drowning in debt, supporting up to seven relatives each and spending an average of 40% of their meagre wages on transport; will not be able to continue to survive such steep petrol, diesel, gas and paraffin price prices.
The most important source of relief for workers, society and the economy, is to maintain the fuel levy relief whilst oil and fuel prices remain high. This is the most impactful and cost-effective solution to this global crisis. Additional relief should be sought by making public transport more affordable to commuters.
It is critical that the Reserve Bank spare society further pain by not increasing the repo rate as this source of inflation is external and not domestic driven. Workers’ meagre wages must be protected from further bleeding.
The private sector must end its investment strike and contribute towards an economic and social relief package to kickstart a stagnant economy and give hope to an under-siege working class. Government with the support of public and private financial institutions must put in place a bold stimulus package to kickstart an under-siege economy.
COSATU will continue to engage government on a package of bold, progressive and decisive measures to cushion workers, the poor and the economy from this global crisis.
Issued by COSATU
Matthew Parks (COSATU Parliamentary Coordinator)
Mobile: 082 785 0687
Unemployment in South Africa has reached crisis proportions. At 43.7% (including “discouraged job-seekers, who are clearly also unemployed), nobody can deny that we are sitting on a ticking time-bomb. Ignoring it is turning a festering wound into a soon-to-be-amputated limb.
In 1982, Marie Jahoda, a British social scientist, developed the Jahoda Latent Deprivation Model to explain how unemployment affects individuals beyond just financial insecurity. She described unemployment as a serious contributor to mental illness, causing anxiety, stress, purposelessness, depression, shame, guilt and apathy. Employment, she said, meets five essential needs: time structure, social contact, shared goals/collective effort, status/identity and regular activity.
With your job gone, you not only lose income; you also lose these psychological benefits, leading to deprivation and potential mental distress.
This is so true in South Africa, where some unemployed people lose all inhibitions to scratch in bins to earn a living. Marriages and families break up because of a lack of income. The unemployed turn to alcohol and other vices for a temporary reprieve from their daily hardships. Societal problems range from crime, health, mental health, gender-based violence, gangsterism and alcohol and drug abuse, to name but a few.
Youth and women bear the brunt when it comes to unemployment; almost 60% of our youth are unemployed.
The government is responsible
Government policies are mainly the cause of this high unemployment rate, although the legacy of apartheid is also a contributing factor.
Unemployment is a structural problem, and as long as the economy does not grow, unemployment will remain high. Economic growth, however, does not always translate into benefits for the poor and does not always create jobs, because the prime objective of business is profit, not the creation of employment.
Neoliberal policies of the South African government, starting with Gear in 1996, created this roller-coaster ride. The liberalisation of trade that came with Gear flooded our markets with cheap textile imports from China. Capitalists are not patriotic, and the local bunch rushed to bring in the cheap imports, which devastated our local textile industry. Economic growth and huge profits for the commercial sector, but totally destructive for the textile manufacturing sector. The result was factory closures and the loss of thousands of jobs. Capitalists in the textile industry could easily move on, diversify into other industries or find new business opportunities. But for the millions of workers, it is a totally different story.
Neoliberalism is an economic ideology influenced by free-market ideologues such as Milton Friedman. It emphasises free-market principles, deregulation and reduced government intervention in the economy. This is at odds with South Africa as a developing nation. It reinforces the old wealth and financial patterns of colonialism, apartheid and capitalism. Economically, we are held in the stranglehold of the West, which controls trade and the global economy and makes all the rules.
The South African government is forever trying to attract foreign direct investment and put in place policies and programmes that will get multi-national corporations to invest. Like our local capitalists, the multi-national corporations only have an appetite for mega profits, and as we have seen, will desert our economy at the earliest threats to their profit margins. They also want to dictate to our country the terms of their economic engagement.
We have witnessed some multinational car manufacturers relocating to other countries, where they believe they can make bigger profits, and some steel manufacturers, like AccelorMetal, also indicating that they will close soon, putting thousands of jobs at risk, swelling the ranks of the unemployed.
Corruption, mismanagement and government incompetence also play a big role in driving away investment and causing unemployment. All of these factors played a huge role in load shedding and the massive increases in electricity prices, and weakened the rand, putting a premium price on fuel; these are all factors driving up the cost of doing business in South Africa. The higher the cost of doing business, the less appetite businesses have to spend on wages, which they, in many cases, regard as a necessary evil. At the slightest provocation or opportunity, they will offload their workforce.
Unemployment destroys society
Stats SA’s Social Profile of South African Youth 2014-2024 flags poverty, crime, education and the labour market as key issues shaping youth in South Africa. It identifies youth unemployment as a major driver of crime among youth, decrying the fact that only 27.7% of youth are employed. The Western Cape, KZN and Eastern Cape, regarded as youth-heavy provinces with high unemployment rates, also have high murder rates and violent crimes. The Eastern Cape had a murder rate of 63.5, the Western Cape 61.1 and KZN 52.2 murders per 100,000 in 2023. Over 55,000 youths, aged 14 -25, are imprisoned in South Africa: 9,000 for economic crimes and 16,000 for aggressive, violent crimes.
Deploying the army is only a stopgap solution, and, in our experience, the problem will persist once the army is withdrawn.
Unemployment and poverty contribute heavily to health issues like diabetes, high blood pressure, heart disease and other lifestyle diseases. The World Health Organisation (WHO) emphasises that these diseases (cardiovascular disease, cancer, diabetes and chronic respiratory diseases) are largely preventable through modifications in diet, physical activity, and reduction of tobacco and alcohol.
Many of these diseases are preventable, and the government is spending a lot of money on treating the symptoms, not the diseases itself. We know the cause of these diseases is not eating properly, not exercising, and substance abuse. We also know the root of these diseases lies in poverty, unemployment, access to proper programmes and tools, and lack of knowledge. If the government is prepared to properly tackle these issues, it can massively reduce its budget of R82.6 billion over the next three years for drugs for treating non-communicable diseases.
Poor and unemployed people have to buy the less nutritious R15 loaf of bread, rather than the R30 and R40 healthier variants. Poor people cannot afford the gym, and do not have the inclination to exercise, considering their heavy burdens. And because of such burdens, they are also more likely to engage in substance abuse like smoking and drinking, and more dangerous substances.
The poor and unemployed do not have the budget or tools for healthy diets and lifestyles.
The government must stop austerity measures that push more and more people into the ranks of the unemployed and onto the margins of poverty.
Revise the EPWP
The government must have a deep dive assessment of all EPWP programmes and overhaul or abolish them. At the moment, they keep our people, including the youth, in bondage and perpetual slavery, working for slave wages. They get paid below the minimum wage and are not covered under the LRA and BCEA. In very few instances do they train our youth in new skills to empower them to find work.
Every year between 570,000 and 650,000 youth matriculate, 572,983 in 2023, 614,562 in 2024, and 650,000 in 2025. Those are only the ones who passed, because in 2025, 900 000 learners wrote the matric exams. And these numbers do not include the many dropouts in primary and high school every year.
And did the almost two million learners who registered for matric between 2023 and 2025 find work? Work has to be found for them, but can our economy cope with such a high demand for jobs? How do we do this, year after year?
Declare an emergency
The government has to admit that it has a massive problem of unemployment on its hands and declare unemployment a national emergency.
An unemployment rate above 40% is definitely a national crisis, and should be treated by the government as such. Unemployment should stop being marginalised and be regarded as an important economic indicator, a labour market state that signals dysfunction and inefficiency. It should be treated as a socio-economic condition in need of urgent attention.
The government should partner with the organisations of the unemployed to find a solution to the unemployment crisis: organisations like B2WC, Assembly of the Unemployed, Botshabelo Unemployed Movement and the Unemployed People’s Movement, as well as trade union federations like Cosatu and Saftu. They should partner to develop programmes to continuously create permanent, decent and dignified employment.
Let’s work together to make it our mission for future generations to not know the word or meaning of unemployment.
Moegsien Ismail is the Media Officer of Back To Work Campaign (B2WC), an unemployed workers’ organisation, organising the Unemployed in the broader Cape Town Metropolitan area, and a member of the Assembly of the Unemployed (AOU). B2WC especially advocates for the Expanded Public Works Programme (EPWP) to be abolished or reformed, and not to be used by the City of Cape Town as a wage-bill cost-cutting exercise.
SACP general secretary Solly Mapaila and EFF leader Julius Malema. Picture: (Sup)
New structure will oversee campaigns on industrial policy, public services and social protection
The SACP-organised Conference of the Left resolved to establish a new Council of the Left as a permanent co-ordinating structure aimed at unifying progressive formations around campaigns, political education and mass mobilisation.
The council, which will have its first sitting in six weeks, would not become a political party or contest elections but would instead co-ordinate action among trade unions, political parties, student organisations, civic groups, faith formations and community movements.
The conference resolved the council’s first meeting must take place within six weeks, and it will oversee a 12-month programme of action with measurable outcomes in key policy and mobilisation areas.
“The current social relief of distress grant is inadequate and falls far below what is required for a dignified life. The conference notes millions who require income support remain excluded through restrictive criteria, administrative barriers and underfunding.
“The struggle for a universal basic income grant must therefore be linked to expanded social protection, redistribution of wealth, land justice and the construction of economic alternatives that place human need before profit,” reads the document.
The ANC stayed away from the conference, but several of its traditional alliance and affiliate partners were represented at the gathering, including the SACP, Cosatu, Cosas, Sasco and Sanco.
The conference brought together left-wing parties and organisations seeking to co-ordinate opposition to what they described as the ANC’s increasingly neoliberal policy direction under the government of national unity (GNU).
EFF leader Julius Malema and SACP general secretary Solly Mapaila used the event to attack the ANC-DA partnership, arguing it had deepened inequality, unemployment and economic exclusion.
The conference also reflected growing frustration in sections of the broader liberation movement, with the SACP increasingly distancing itself from the ANC over electoral strategy and governance choices. ANC secretary-general Fikile Mbalula dismissed the gathering as anti-ANC.
DA leader Geordin Hill-Lewis focused on the divisions to criticise the ANC and the leftist bloc, describing in his weekly newsletter their politics as outdated and economically damaging. Hill-Lewis argued South Africa needed accelerated economic reform and private sector-led growth rather than expanded state intervention.
His comments highlighted the tensions in the GNU, where the DA continues to position itself as a reformist alternative while governing alongside the ANC nationally.
The National Education, Health and Allied Workers’ Union [NEHAWU] congratulates South African Communist Party [SACP] and other organisations of the working class for hosting a historic and successful Conference of the Left which ended yesterday 31st May 2026.
The conference was held under the theme “Building a Left Movement for Working-Class and Popular Power”. Indeed, the conference was characterised by robust and frank discussions on how to rebuild the organised power of the working class and the poor. As NEHAWU, we are inspired by the qualitative outcomes of the conference as enshrined in the Declaration for Working-Class and Popular Power.
We proudly declare that the conference has indeed invigorated the Socialist-Axis to fight against imperialism and the barbaric system of capitalist exploitation and oppression. The Socialist-Axis emerges from the conference more determined and resolute to provide an alternative system to capitalism.
NEHAWU as a union that follows the line of a militant class-oriented trade union movement rooted in struggles of the working people of the world, we welcome the conference’s affirmation of progressive internationalism, radical Pan-Africanism and the struggle for peace as strategic principles of the Left.
We welcome the conference’s stand against war, militarism, occupation, sanctions, regime-change operations and imperialist aggression. Furthermore, we welcome the solidarity expressed by the conference with the oppressed masses of the world, including the peoples of Palestine, Cuba, Venezuela, Iran, Western Sahara and the Sahel. The Conference expressed unwavering solidarity with Cuba and called for a South African Cuba Solidarity and Anti-Blockade Bill.
The conference was convened at a time when our National Democratic Revolution is at a point of derailment. Hence, as NEHAWU, we fully agree with the conference’s analysis that South Africa is in a deep structural crisis rooted in capitalism, neo-colonialism, imperialism, monopoly power, patriarchy, racism, austerity, unemployment, hunger, inequality, social violence, ecological destruction and the unfinished transformation of society after 1994. This, therefore requires the Socialist-Axis to provide strategic and tactical working class leadership to help the class to map the way out of this disconcerting socio-economic and political conjuncture.
We welcome the Conference declaration that the Left must move from critique to the construction of a credible alternative economic plan for South Africa. This plan must include fiscal policy, monetary policy, industrial policy, trade policy, public investment, ownership and control of strategic sectors, developmental finance, democratic planning, and the allocation of resources towards employment, production, public services and social ownership.
We also welcome the pronouncement for the nationalisation of the South African Reserve Bank and a fundamental review of its mandate, ownership, governance and accountability. Monetary policy must serve employment, industrialisation, developmental finance, public investment, transformation and the needs of the working class and poor.
As a health union, we fully support the declaration to defend a fully funded National Health Insurance system against private capitalist capture. NHI must not become a mechanism for funding the privatisation of healthcare or subsidising private providers at public expense. It must form part of the wider struggle for redistribution, public provision, equality, social rights and the decommodification of healthcare.
We welcome the adopted first-phase Programme of Action organised around eight clusters which include; Economic transformation, work and livelihoods, Cost of living, public services and social protection, Land, restitution, redistribution and local democratic economies, Public health, NHI and social reproduction, Social violence, community safety and working-class unity, Climate justice, energy sovereignty and the just transition, Internationalism, Pan-Africanism, peace and anti-imperialist solidarity and Review of the 1996 Constitution, state power and democratic transformation.
This conference must serve as a turning moment for the Socialist Axis to rebuild a powerful left movement for our class and popular power.
Lastly, our 13th National Congress on the 26 – 29 June 2026 will take an advantage of receiving a detailed report about the conference of the left for proper analysis so as to draw a deliberate role and program NEHAWU must play and develop in the practical implementation of critical core of the declaration as its responsibility of the political tasks, as part of the most organised contingent of the working class, for itself and the preparations of COSATU 15th National Congress scheduled in September 2026 and in a broader working class revolution.
END
Issued by NEHAWU Secretariat.
Zola Saphetha (General Secretary) at 082 558 5968; December Mavuso (Deputy General Secretary) at 082 558 5969; Lwazi Nkolonzi (NEHAWU National Spokesperson) at 081 558 2335 or email: lwazin@nehawu.org.za